Inquiry
A quote is compared across insurers
A broker places the same risk with more than one insurer and compares terms.
Coming soon Professional & Creative Services
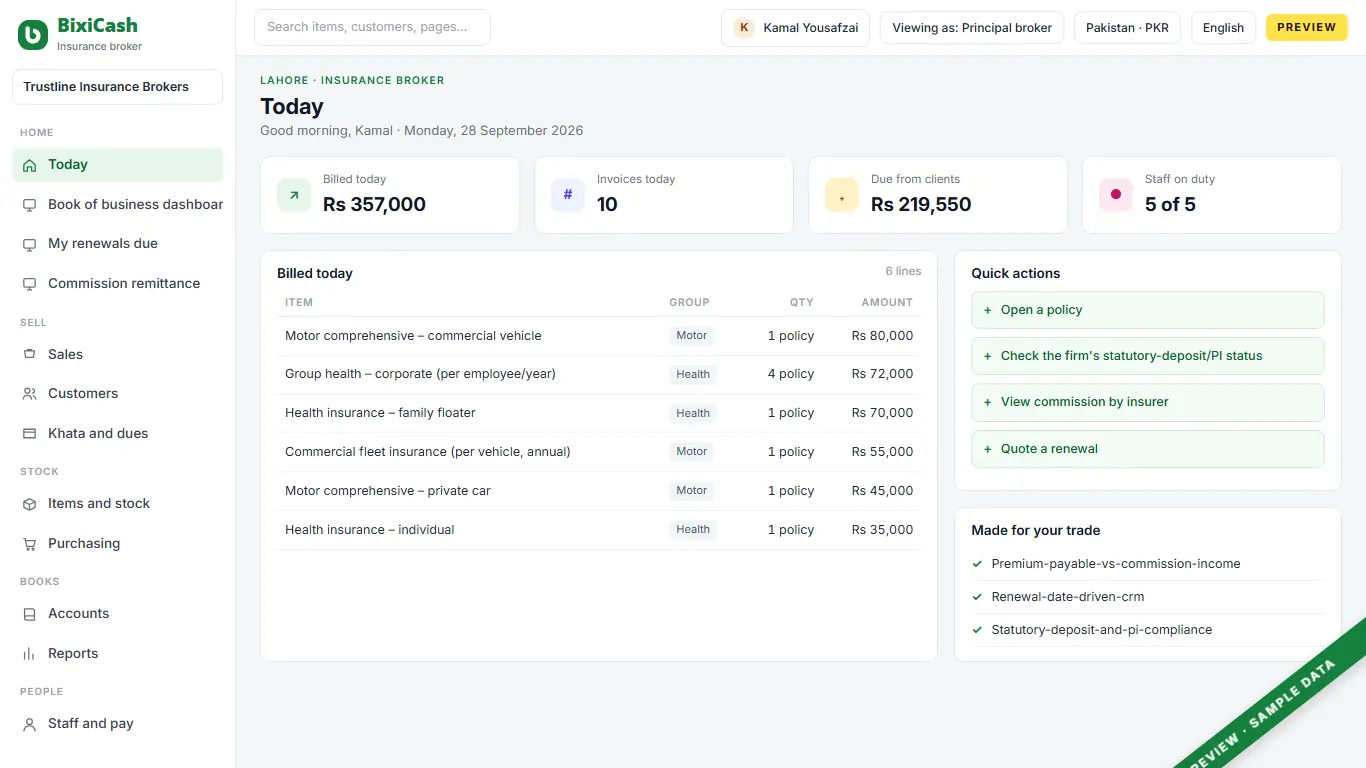
For a brokerage placing motor, health, fire and life cover: premium collected for the insurer stays a liability, only the commission is the broker's own income, and a renewal never slips past unnoticed.
A working day
Inquiry
A broker places the same risk with more than one insurer and compares terms.
On issue
Premium is collected from the client when the policy is issued.
After collection
The premium, less the broker's commission, is remitted to the insurer.
Ongoing
Policies coming due in the next 30 days are called or messaged ahead of expiry.
Monthly
What the insurer actually paid is checked against what was expected.
What goes wrong today
Premium collected on the insurer's behalf is at risk of being treated the same as the broker's own commission.
A policy lapses because nobody worked the renewal list in time.
What an insurer actually pays doesn't line up with what was expected, and finding the gap takes real time.
A mid-term cancellation's pro-rata premium refund and commission clawback are calculated case by case.
What it does
Parts marked Coming soon are on the way; founding shops get them first, at no extra charge.
A premium receipt will post as a liability owed to the insurer. Commission will count as the broker's own income only once the insurer's statement confirms it.
A renewal list will surface every policy coming due, sorted by premium value, instead of a spreadsheet kept from memory.
The firm's own statutory deposit and professional-indemnity insurance status will show as a first-class fact, not tracked outside the system.
Premium due from a client, though usually collected up front, runs on the same accounts-receivable engine as any invoice.
One commission engine will cover first-year and renewal commission by insurer and by agent.
An approval flow like this is already shown in our demo elsewhere; policy documents and claims paperwork per client are coming to this trade next.
A renewal due date pre-fills a WhatsApp message to the client; a person presses send.
Who uses it
Principal broker
manages insurer relationships and large-account placement, and watches the firm's own compliance status.
Sales / relationship agent
quotes across insurers, writes new business and works the renewal list.
Claims / renewal coordinator
tracks renewal dates and assists with claims documentation.
Accounts
collects premium, remits to insurers, and reconciles commission statements.
Behind the counter
The screens for your trade sit on a full set of books. These parts come with it.
Double-entry books, statements, period close.
Cash, bank, cheques and reconciliation.
Orders, supplier bills and what you owe.
Quotations, orders, invoices, delivery notes.
One staff register, attendance, pay runs.
Machines and vehicles, and their wear.
The numbers an owner asks for each morning.
The price
Introductory price. Local taxes are added where they apply. A second shop costs the same as the first. Prices for countries without their own page, in USD, as of 28 Sep 2026.
The first 50 shops in each country get free setup and data import with a yearly plan, and today's price locked for two years.
Claim a placeThis trade does not have its own price line yet. The price shown is our retail line, and we confirm it when we quote.
Straight answers
No. Only the commission is meant to be ours; the premium-as-liability posting isn't built yet.
Not yet. A renewal list sorted by date is planned.
Planned, as part of the same commission engine; today this would still be a manual check.
Planned; not built today, and we haven't verified whether Pakistani rules require client premium to sit in a segregated account the way UK client-money rules do.
We haven't confirmed current slab rates per class; treat any rate as illustrative until verified.
Twenty minutes on a call. We show your day on the screen, with your words and your stock.